

Why this matters: Real estate sales agents are watching a slight trend of increasing inventory for sale, a new experience for those not part of the market buildup in inventory during the two years prior to the 2020 recession. The consequence of a consistently growing for-sale catalog forces a reduction in asking prices as occurred in 2023 when inventory last bottomed.
A buyer’s market arrives, and agents pivot
California’s inventory of homes available for sale is now in expansion mode as a follow-on from an unparalleled disruption-driven contraction of sales volume:
- precipitated by the pandemic fueled buying spree of 2021 which cannibalized the following year’s sales; and
- aggravated by the flow-through of uncertain economic conditions in California, including:
- high and rising mortgage rates;
- employment stagnating;
- abnormal increases in consumer prices; and
- tariff, military and immigration ruptures.
For-sale inventory in California’s largest metros averages 1.9% below a year earlier for September 2026, from data released by Zillow. Although the overall pattern shows a recovery from 2023’s post-pandemic inventory low, it has not kept up with strides made through early 2026.
The number of California properties publicly offered as available in the year-to-date sales by September 2026 is -2.1% lower in most counties than the same time period a year earlier. Total available inventory for the larger metro areas are still far fewer in 2026 than in 2018 and 2019 pre-recession years — the last “normal” years before the covid pandemic and its 2021 buying spree.
By 2025, low-tier priced housing had the lowest level of inventory available for sale or rent. No surprise here, as today’s mid- to high-tier pricing is out of range for most of our employed population.
Consider this: wealthy buyers are historically the first to taper off acquiring property. As they sell, their retreat causes an earlier buildup of excess high-tier inventory than occurs in lower tiers. Thus, a decline in pricing occurs first in high-tier priced housing followed by mid-tier, then low-tier housing.
The wealthy experience a decline (or increase) in their income before jobholders do. Profits and interest from investments decline before growth in jobholder numbers peaks and starts its recessionary decline as California witnessed in 2025.
However, 2026’s uncertainty around employment, trade taxes, and rising costs — especially in areas like real estate construction — all contrast against buoyed Wall Street bets kept high by a corporate dash to build up AI and the military-industrial complex. The faux buildup inverts the cycle, so workers looking forward will be the first to feel the effects of the looming, but yet to be announced, recession.
Today’s high price point levels asked by sellers and the cyclically higher mortgage rates force buyers reliant on mortgage funding to either:
- wait until sellers reduce their price demands significantly; or
- buy cheaper housing.
Compounding the drag on sales volume, mortgaged homeowners who purchased or refinanced in the past decade are less willing to sell and relocate to an upgrade now that today’s mortgage rates and payments greatly exceed those on their present mortgage. Wide-spread pandemic refinancing is now inhibiting owner turnover, as well as reverse mortgages, significant factors reducing transactions and broker fees.
One solution is the assumption of pandemic mortgages by buyers when arranged without lender interference. But mortgage assumptions are not yet in use by seller agents to expedite sales volume.
Additional drags on seller willingness to turn over their occupancy and ownership are the readily available HELOCs and reverse mortgages for retired owners of single family properties, as well as the new ADU permits available to most SFR homeowners.
Further, the California real estate slowdown in sales volume, underway since mid-2022, has worsened with the sudden destabilization of global immigration and trade arrangements brought on by current wars.
For seller agents, highly leveraged property owners who experience a loss in income and equity wealth are placed in the position of unconventional sellers. As forced sales, these properties are added to for-sale inventory without the seller purchasing a replacement property. Once forced to sell, these sellers who are employed become long-term tenants to satisfy their housing needs.
The growth of inventory for sale has consequences: prices of property begin to decline as sellers seek to attract a buyer from a reduced number of potential consumers of housing. Buyers, confronted with swelling choices and declining prices, initially tend to take a wait-and-see approach before they are willing to step up and acquire a property.
Today, no fear of missing out (FOMO) remains from the pandemic period. The buyer retreat presently underway ends when buyers perceive prices have reached their bottom level and several months of sales activity indicates prices are on the rise.
Looking ahead, expect for-sale inventory to increase as 2026 draws to a close while buyers have become more cautious.
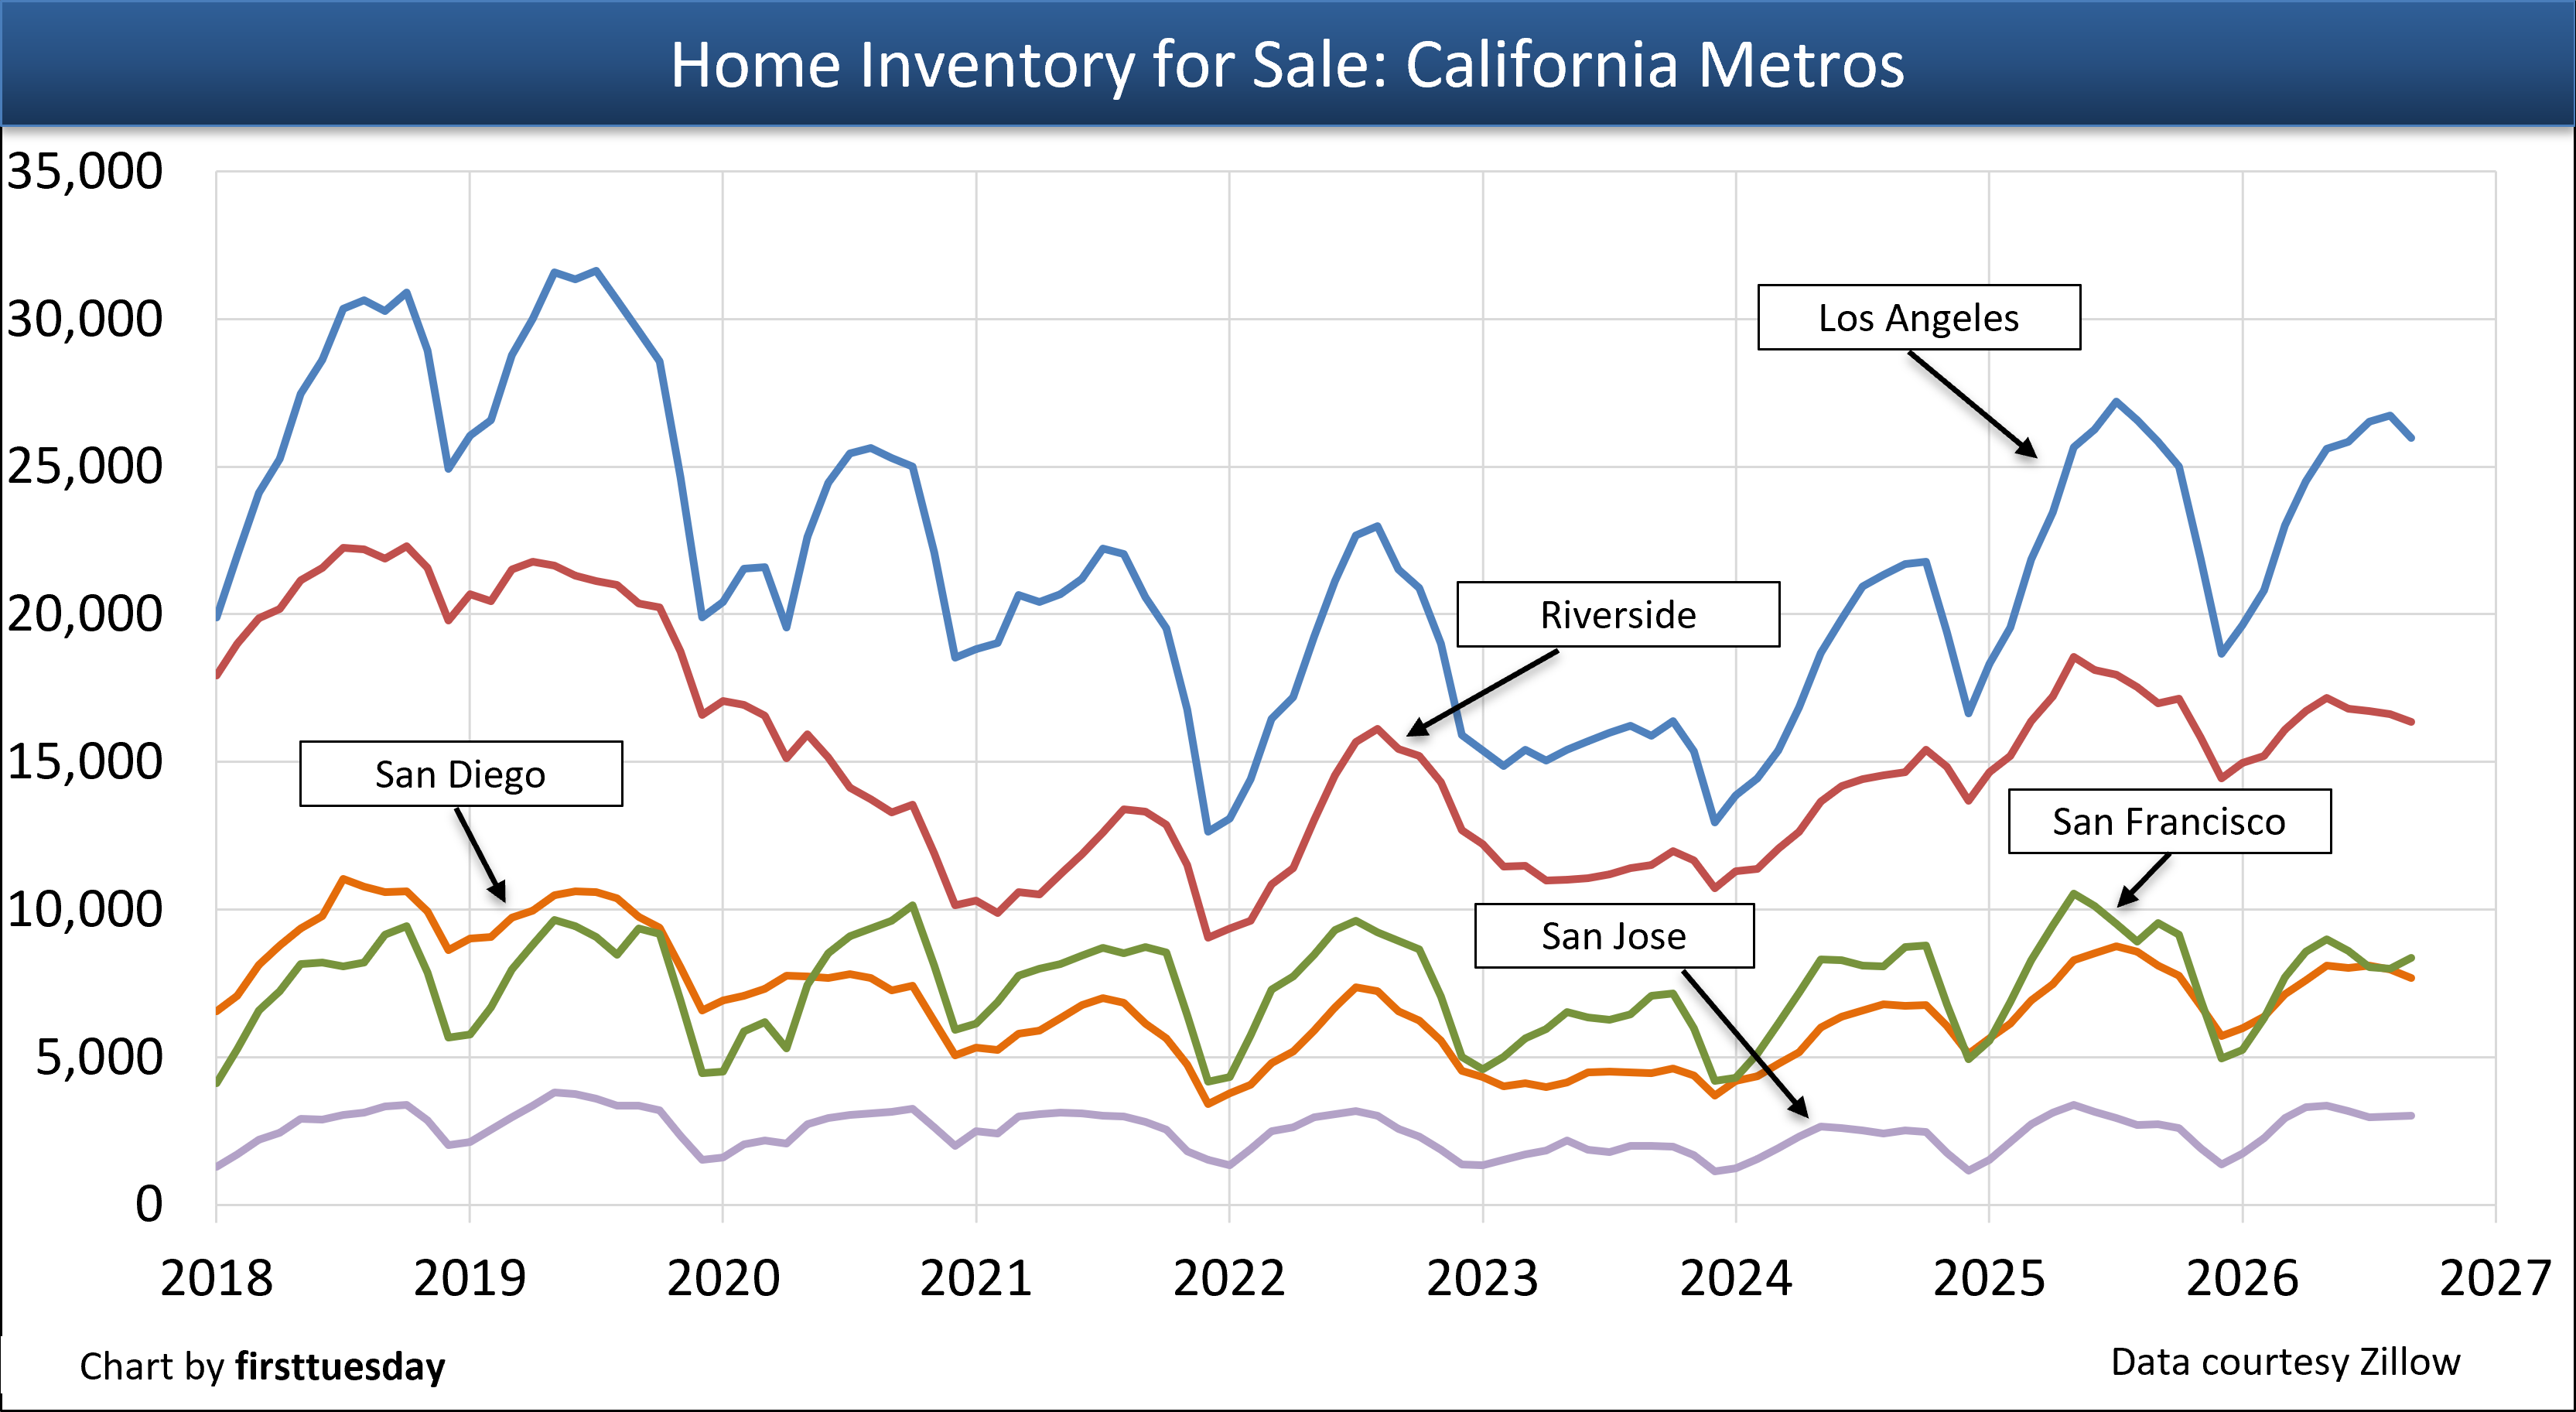 Chart update 6/22/26
| September 2026 | September 2025 | Annual change | |
| Los Angeles for sale inventory | 26,000 | 25,800 | +0.5% |
| Riverside for sale inventory | 16,300 | 17,000 | -3.8% |
| San Diego for sale inventory | 7,700 | 8,100 | -4.9% |
| San Francisco for sale inventory | 8,400 | 9,500 | -12.3% |
| San Jose for sale inventory | 3,000 | 2,700 | +10.5% |
The long-enduring seller’s market of previous decades fully reversed course in mid-2022. It has evolved to the initial stage for a full-blown buyer’s market. The shift to a buyer’s market in real estate began with the 2013 cyclical end to ever-lower mortgage rates after 1982. The historically low mortgage rates of 2013 introduced our present roughly 30-year half cycle of generally rising mortgage rates.
As for real estate agents in property sales and leasing, a steady income from fees in 2026-2028 requires agents to consider a pivot in their practice to cash-heavy users of property, whether owners or tenants, residential or commercial.
A buyer with the willingness to buy property and ability to use accumulated wealth to acquire a home has a logic for buying now. The justification for a cash buyer to pay a high price to purchase property today is that the price is offset by the present value of the annual spread between the:
- greater interest rate avoided on a mortgage; and
- lesser interest rate lost on savings or bonds used to purchase the property.
Also consider the amount of the implicit rental income the SFR property will generate if rented. The implicit rent amount is not incurred by the buyer-occupant – it is saved – by an all-cash price. A buyer agent’s BPO evaluating the rent amount based on their CMA for rents paid by tenants in similar property set the buyer’s implicit rent amount saved.
Thus, the opportunity cost of the amount of interest lost on the cash savings is far less than rent for the property acquired. This logic is further justification for paying today’s higher price for property – up to a ceiling price – as ownership itself is not strapped with high mortgage rates for the price paid.
Expect property prices to bottom around 2030 with a trough for maybe 18 months, unlike the four-year trough beginning in the second year of the 2008 recession. As always, a timeline is complicated by disruptions in jobs and financial attitudes brought on by abnormal shifts in economics due to international turmoil and the vicissitudes of inconsistent government action.
The 2001 recession is a classic example of forecasting uncertainties when 9/11 put end to that recession with war and stimulus investments which greatly increased monetary and fiscal outlays. As for the 2020 recession, it never materialized to correct either consumer or asset inflation as the pandemic and government stimulus of all types instantly ended the month long 2020 recession.
Related article:
The cure for an inventory shortage
California’s decade-long inventory imbalance and related housing crisis of low-tier availability have two reasonable bases for resolution:
- decreased demand, via an increase in the number of occupants per existing dwelling or parcel of real estate, a recession-related phenomenon (a process already underway with “rent-a-room” plans becoming an economically acceptable use of empty-nester homes); and
- construction of residential units, enforced and funded by state programs, such as the state pension fund, for low-tier priced housing necessary to support the local workforce.
The years beyond 2026 will see a bit of both. Residential construction is complicated by artificially increased costs of materials and current buyer caution to take on mortgage debt.
Homeownership is below normal rates and rental vacancies are greater than normal rates for the present level of household income in California. This occupancy stress is due to local and statewide inability — resistance — to permit new construction of housing units sufficient to house individuals employed within a community. The concept of “live where you work” is yet to catch on with local policy makers.
To that end, numerous pieces of new legislation and OAG action since 2017 focus on constructing more dwellings in California communities. However, only a few communities with an inclusive mindset are willing to deliver long-term housing policy that positively address the permitting issue. Some officials in coastal communities need judicial enforcement by the OAG to allow permits for additional low-tier housing to skirt the politically pervasive NIMBY crowd’s attitude.
Unless a community permits low-tier housing starts, the community will need rent control ordinances to house those families employed locally. It’s one or the other, as coastal communities have discovered.
Related article:




Vehicle Owner Details are essential for maintaining accurate records and ensuring proper identification of the registered vehicle owner. Complete and correct information helps verify legal ownership, maintain transparency, and prevent unauthorized vehicle transfers or fraudulent activities. It also makes official processes such as vehicle registration, ownership transfer, insurance, and verification easier and more reliable.