

Why this matters: Real estate agents and brokers in 2026 are observing a fourth year of persistent substandard home sales volume, as ripples from the pandemic stimulus frenzy plateau. In 2025 as FRM rates dropped over 80 percentage points, additional buyers did not come forward. Meanwhile FRM rates in 2026 erupted again, inventories of property for sale grew, and will build up with a vengeance until rates or home prices greatly reside.
Homes for sale meet disincentivized buyers
In August 2026, California saw 23,600 escrows close for new and resale home transactions. Sales volume in August dropped 1.8% below the same month one year earlier.
Importantly for trends, year-to-date (YTD) sales volume through August 2026 only rose 0.2% from the 2025 YTD sales figure. This continues a fourth year of flat to weak sales volume, with evolving aggressive consumer inflation reflected in both FRM and ARM rates, and static property pricing insufficient to attract willing buyers.
Job uncertainty and insidious effects from trade and military wars are inducing caution to freeze owner turnover and home building.
Recent home sales trends
Critically, annual sales volume during these four years was 28% below 2019 — the last year in the pre-pandemic sales cycle of ten years with similar sales volume to 2019.
Today, most buyers are waiting until they sense the decline in pricing has passed, evidenced by prices hiting a trough and begining to rise. Be aware your typical homebuyer today knows their math for income-to-mortgage leveraging to set home pricing, thanks to readily available insight.
The developing public uncertainty about political upheaval, trade taxes and immigration hostilities — and then a war — tamps down owner and tenant turnover, and thus sales volume. The property sales volume will suffer from this buyer status quo-type rigor mortis until speculators turn to the real estate market and stop prices from dropping.
Sales volume strikes at pricing
Watch for home sales volume to trail off going into 2027. The U.S. is shifting into an economy not unlike the mid-1960s and mid-1980s stemming from a heightened focus on resetting the military-industrial complex for a war economy which instantly suppresses user turnover.
When home prices decline across all pricing tiers, not just the high tier now underway, recent homeowners with little down payment can only watch as the equity in their home slides underwater. This price-to-mortgage crossover event into negative equity ownership is not likely to begin until a nationwide economic recession brings on a further drop in the number of Californians employed. Also, keep an eye on the slow upward trend currently underway with mortgage foreclosures, a force increasingly compelling owners to sell.
Sales agents can expect the current real estate recession to eventually bring about a return of real estate speculators after prices drop. Speculator acquisitions produce a “dead cat” bounce in both sales volume and pricing.
Within 12 months following the speculator-driven market bounce, home prices historically slip as homebuyers wait — and watch — as prices bottom during that period. It is then that a sustainable sales volume and pricing recovery takes over with the return of end-user homebuyers — and temporarily lower mortgage rates returning for lack of investment opportunities.
Updated October 2026.
Chart 1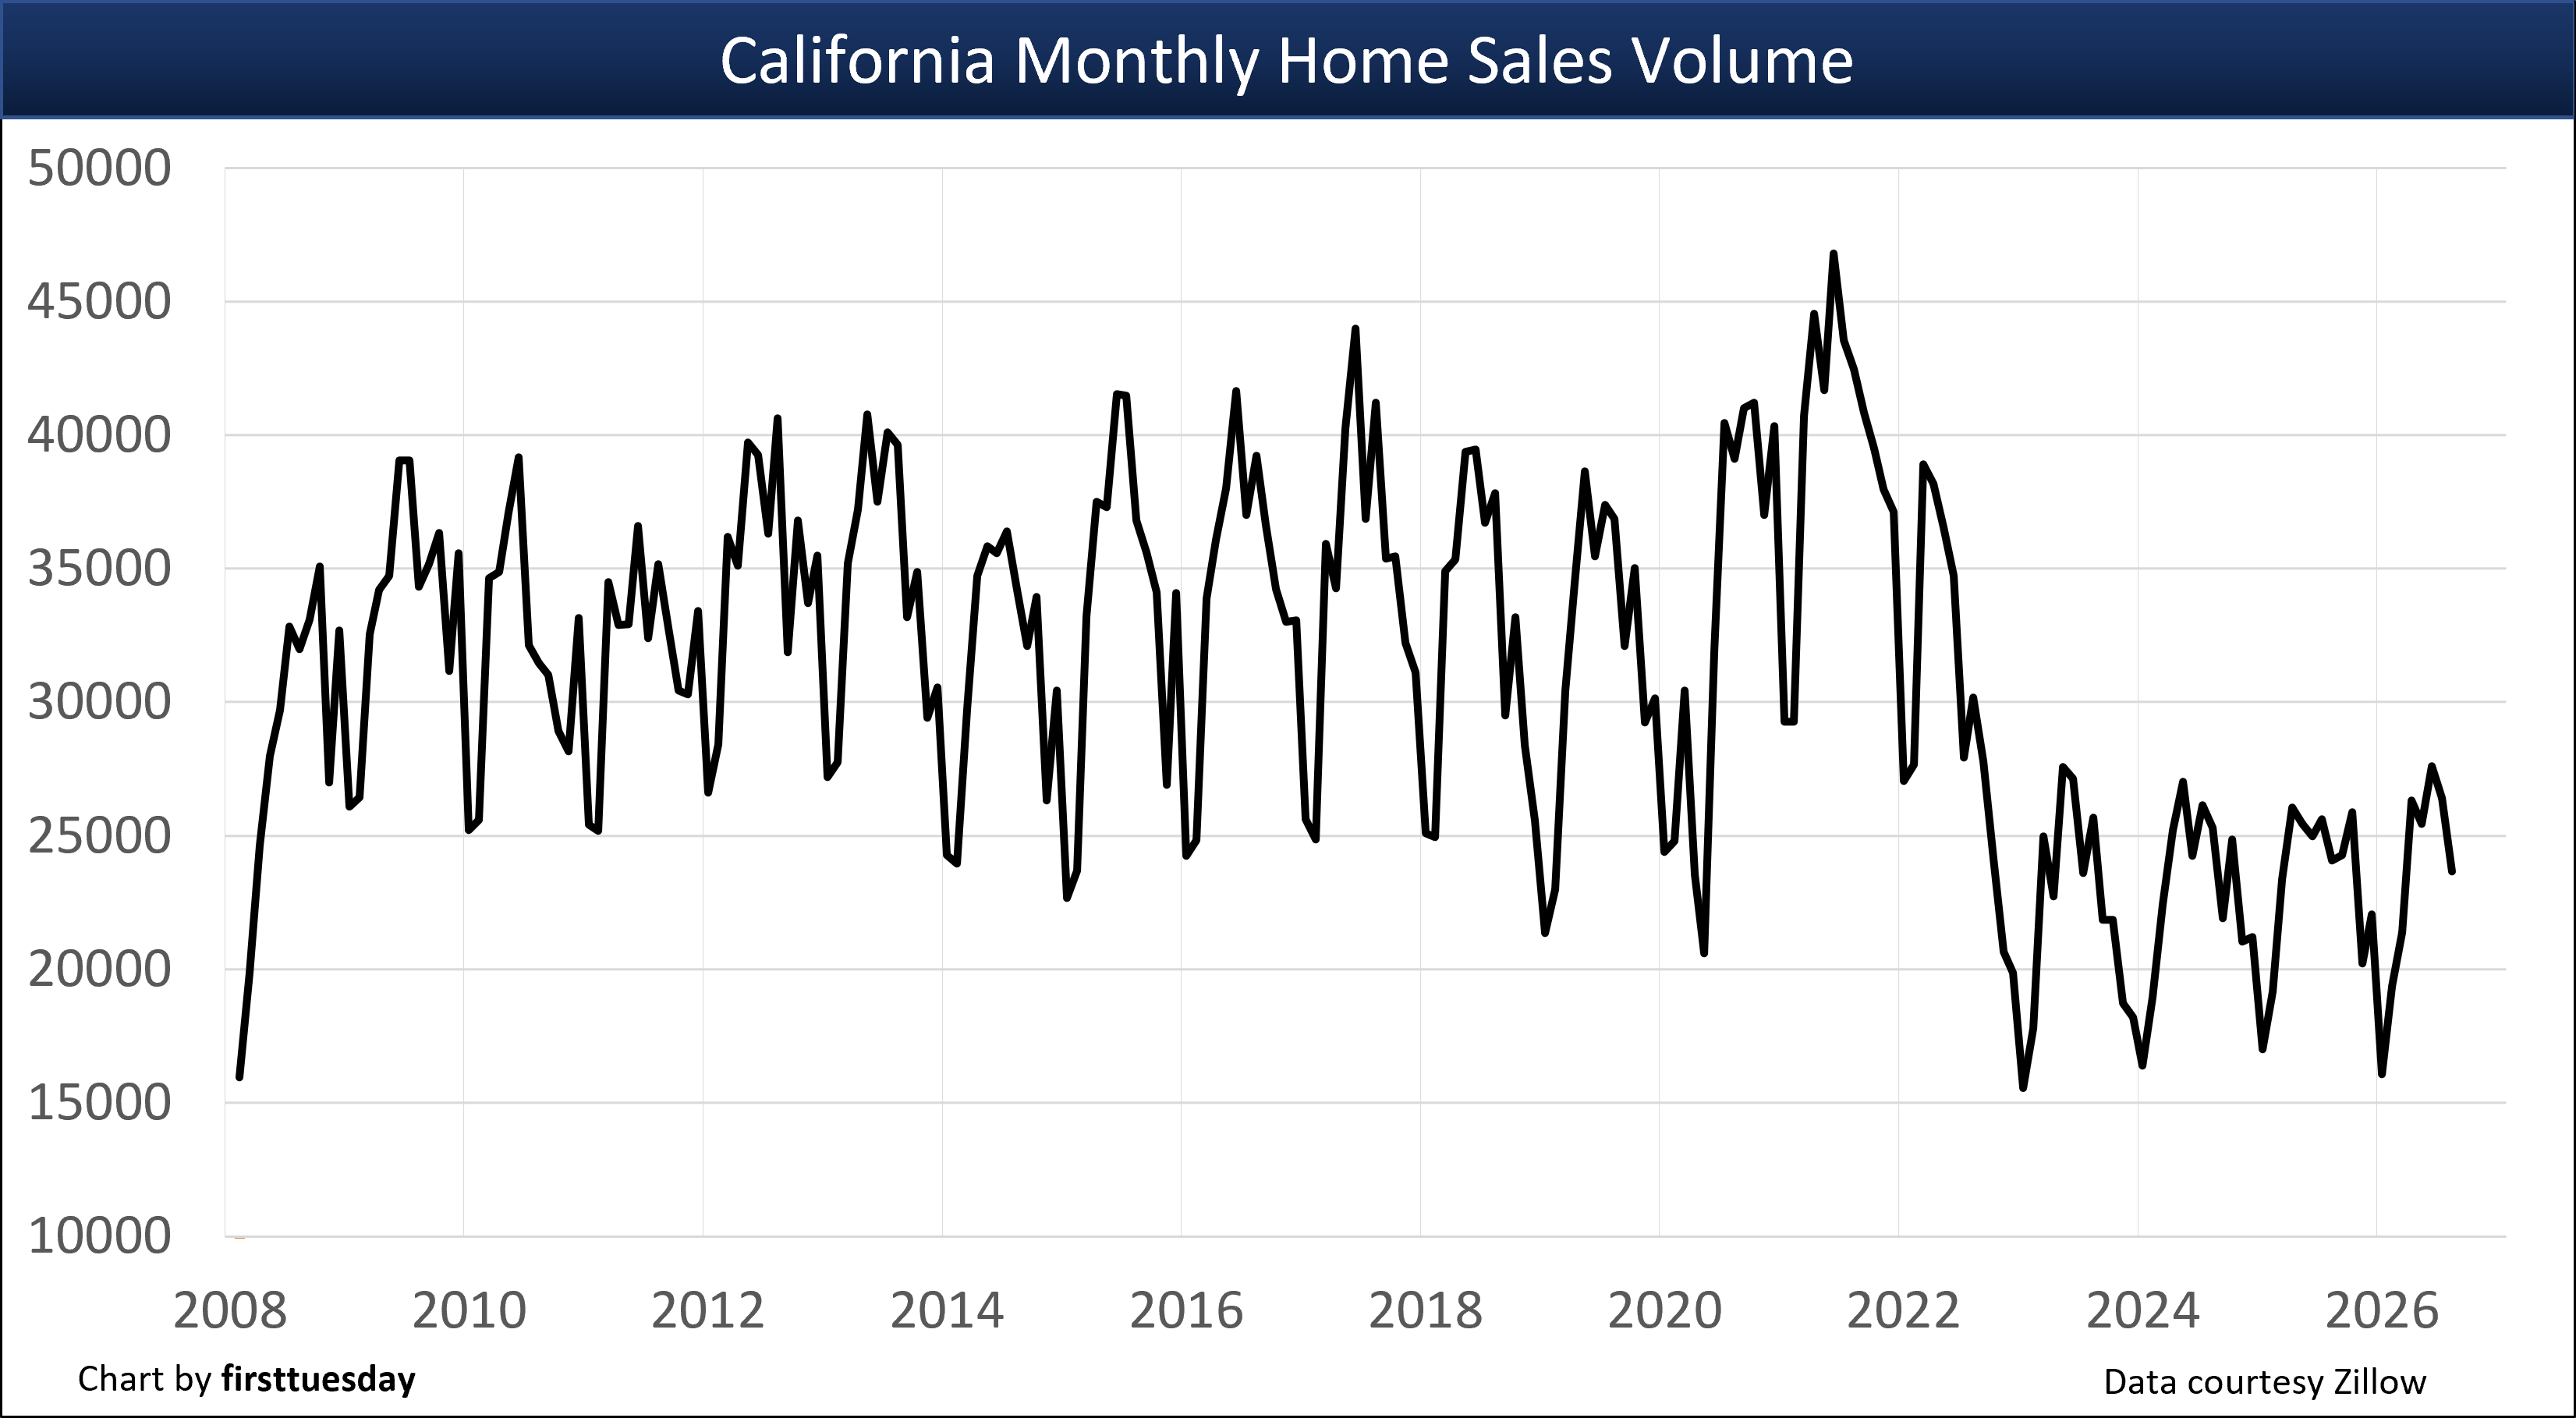 Chart update 9/24/26
August 2026 | August 2025 | YoY change | |
| California home sales volume | 23,600 | 24,100 | -1.8% |
*Data is compiled from Zillow’s sales count on all homes including SFR’s, condominiums and co-operative ownership. Information is gathered from all Metropolitan Statistical Areas (MSA’s) within California.
Home sales fluctuate from month to month for a variety of reasons, all worth an active agent taking time to consider. The most significant reason is the volatility of homebuyer demand. Several factors constantly at work moving the California homebuying market include:
- seasonal motivational differences, an annual sales cycle producing the spring bounce [see Chart 2];
- job market fluctuation;
- mortgage interest rate movement;
- homebuyer saving rates;
- home pricing sought by seller agents;
- turnover rates for tenants and owners;
- negative equity property financials; and
- investor and speculator opportunity perceptions.
Seasonal differences in annual sales volume
It’s normal for home sales volume to rise in the first half of the year and fall after peaking around June.
Chart 2 Chart 2 shows average home sales volume experienced from 2011-2018, the recovery period following the Great Recession. As depicted, the month with the most homes sold monthly during the year close escrow in June. Another upturn takes place in December, as homebuyers seek to wrap up their financial activities before the end of the year.
Real estate agents need not fuss when they hear of falling month-to-month sales volume in the latter half of the year. It is the normal cycle of seasonal progression taking place. To best see a trend watch for year-over sales by comparing:
- recent months this year to the same months last year; or
- the year-to-date period with the same period last year
As a rule, current market activity, whether up or down, is reflected first in sales volume, followed in nine to 12 months by price adjustments in the same direction.
Chart 3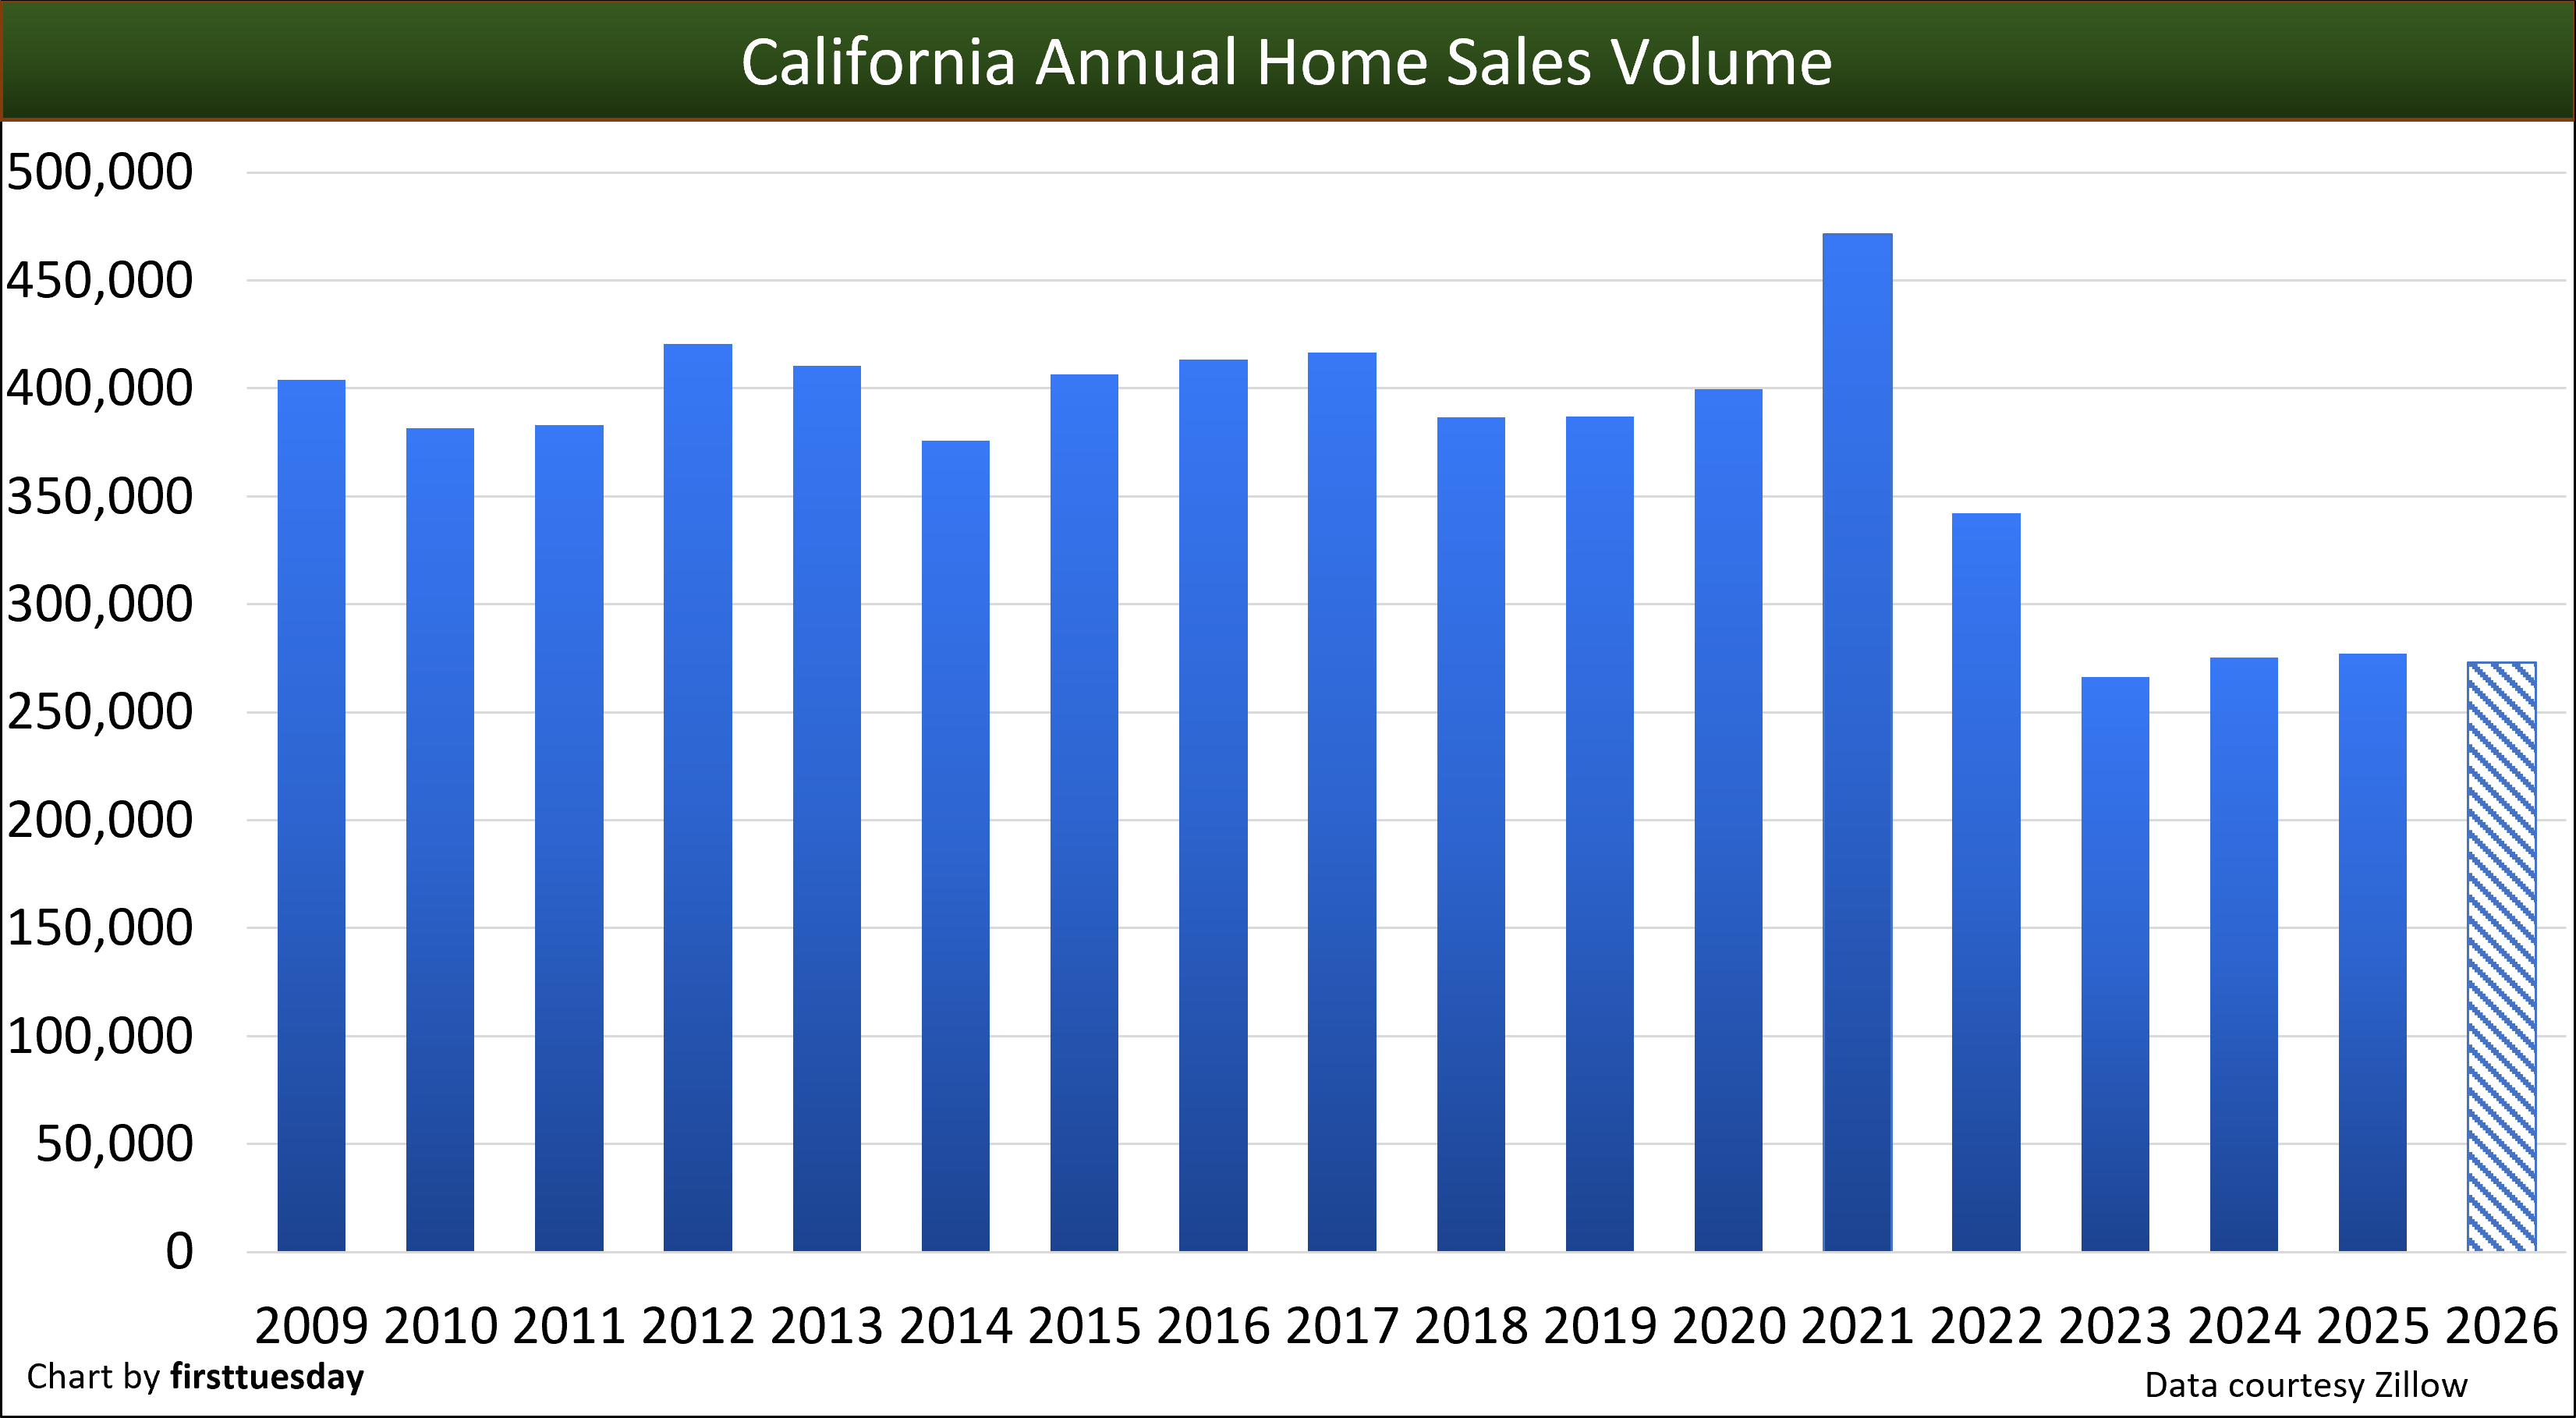 Chart update 9/24/26
| Forecast 2026 | 2025 | 2024 | 2023 | Annual change | |
| Annual home sales volume | 273,000 | 277,100 | 275,300 | 266,400 | +0.1 |
Editor’s note — In the chart above, firsttuesday forecasts 2026 to end below the home sales volume in 2025, based on current sales trends.
To set the stage for a forward look, a review of sales volume in the recent past is helpful:
- 2022 home sales volume peaked early in March and lost all ground gained in the pandemic year of 2021, ending the year 24% below 2021, but only 12% below 2019, the last “normal” year for home sales before the pandemic stimulus upended market dynamics;
- 2023 home sales volume lost a further 22% over the prior year, the consequence of buyers pulled forward to buy in 2021 using historically low mortgage rates for funding;
- 2024 home sales stabilized from the prior year, suggesting the end of the ripple effect from pandemic economics;
- 2025 continued the stagnant sales trend of the prior two years; and
- 2026 matches the slow sales pace of 2025 going into the fall, which is expected to decrease further as international conflict and the highest FRM rates since the pandemic causes buyers to rethink large purchases and costly mortgage debt.
Chart 4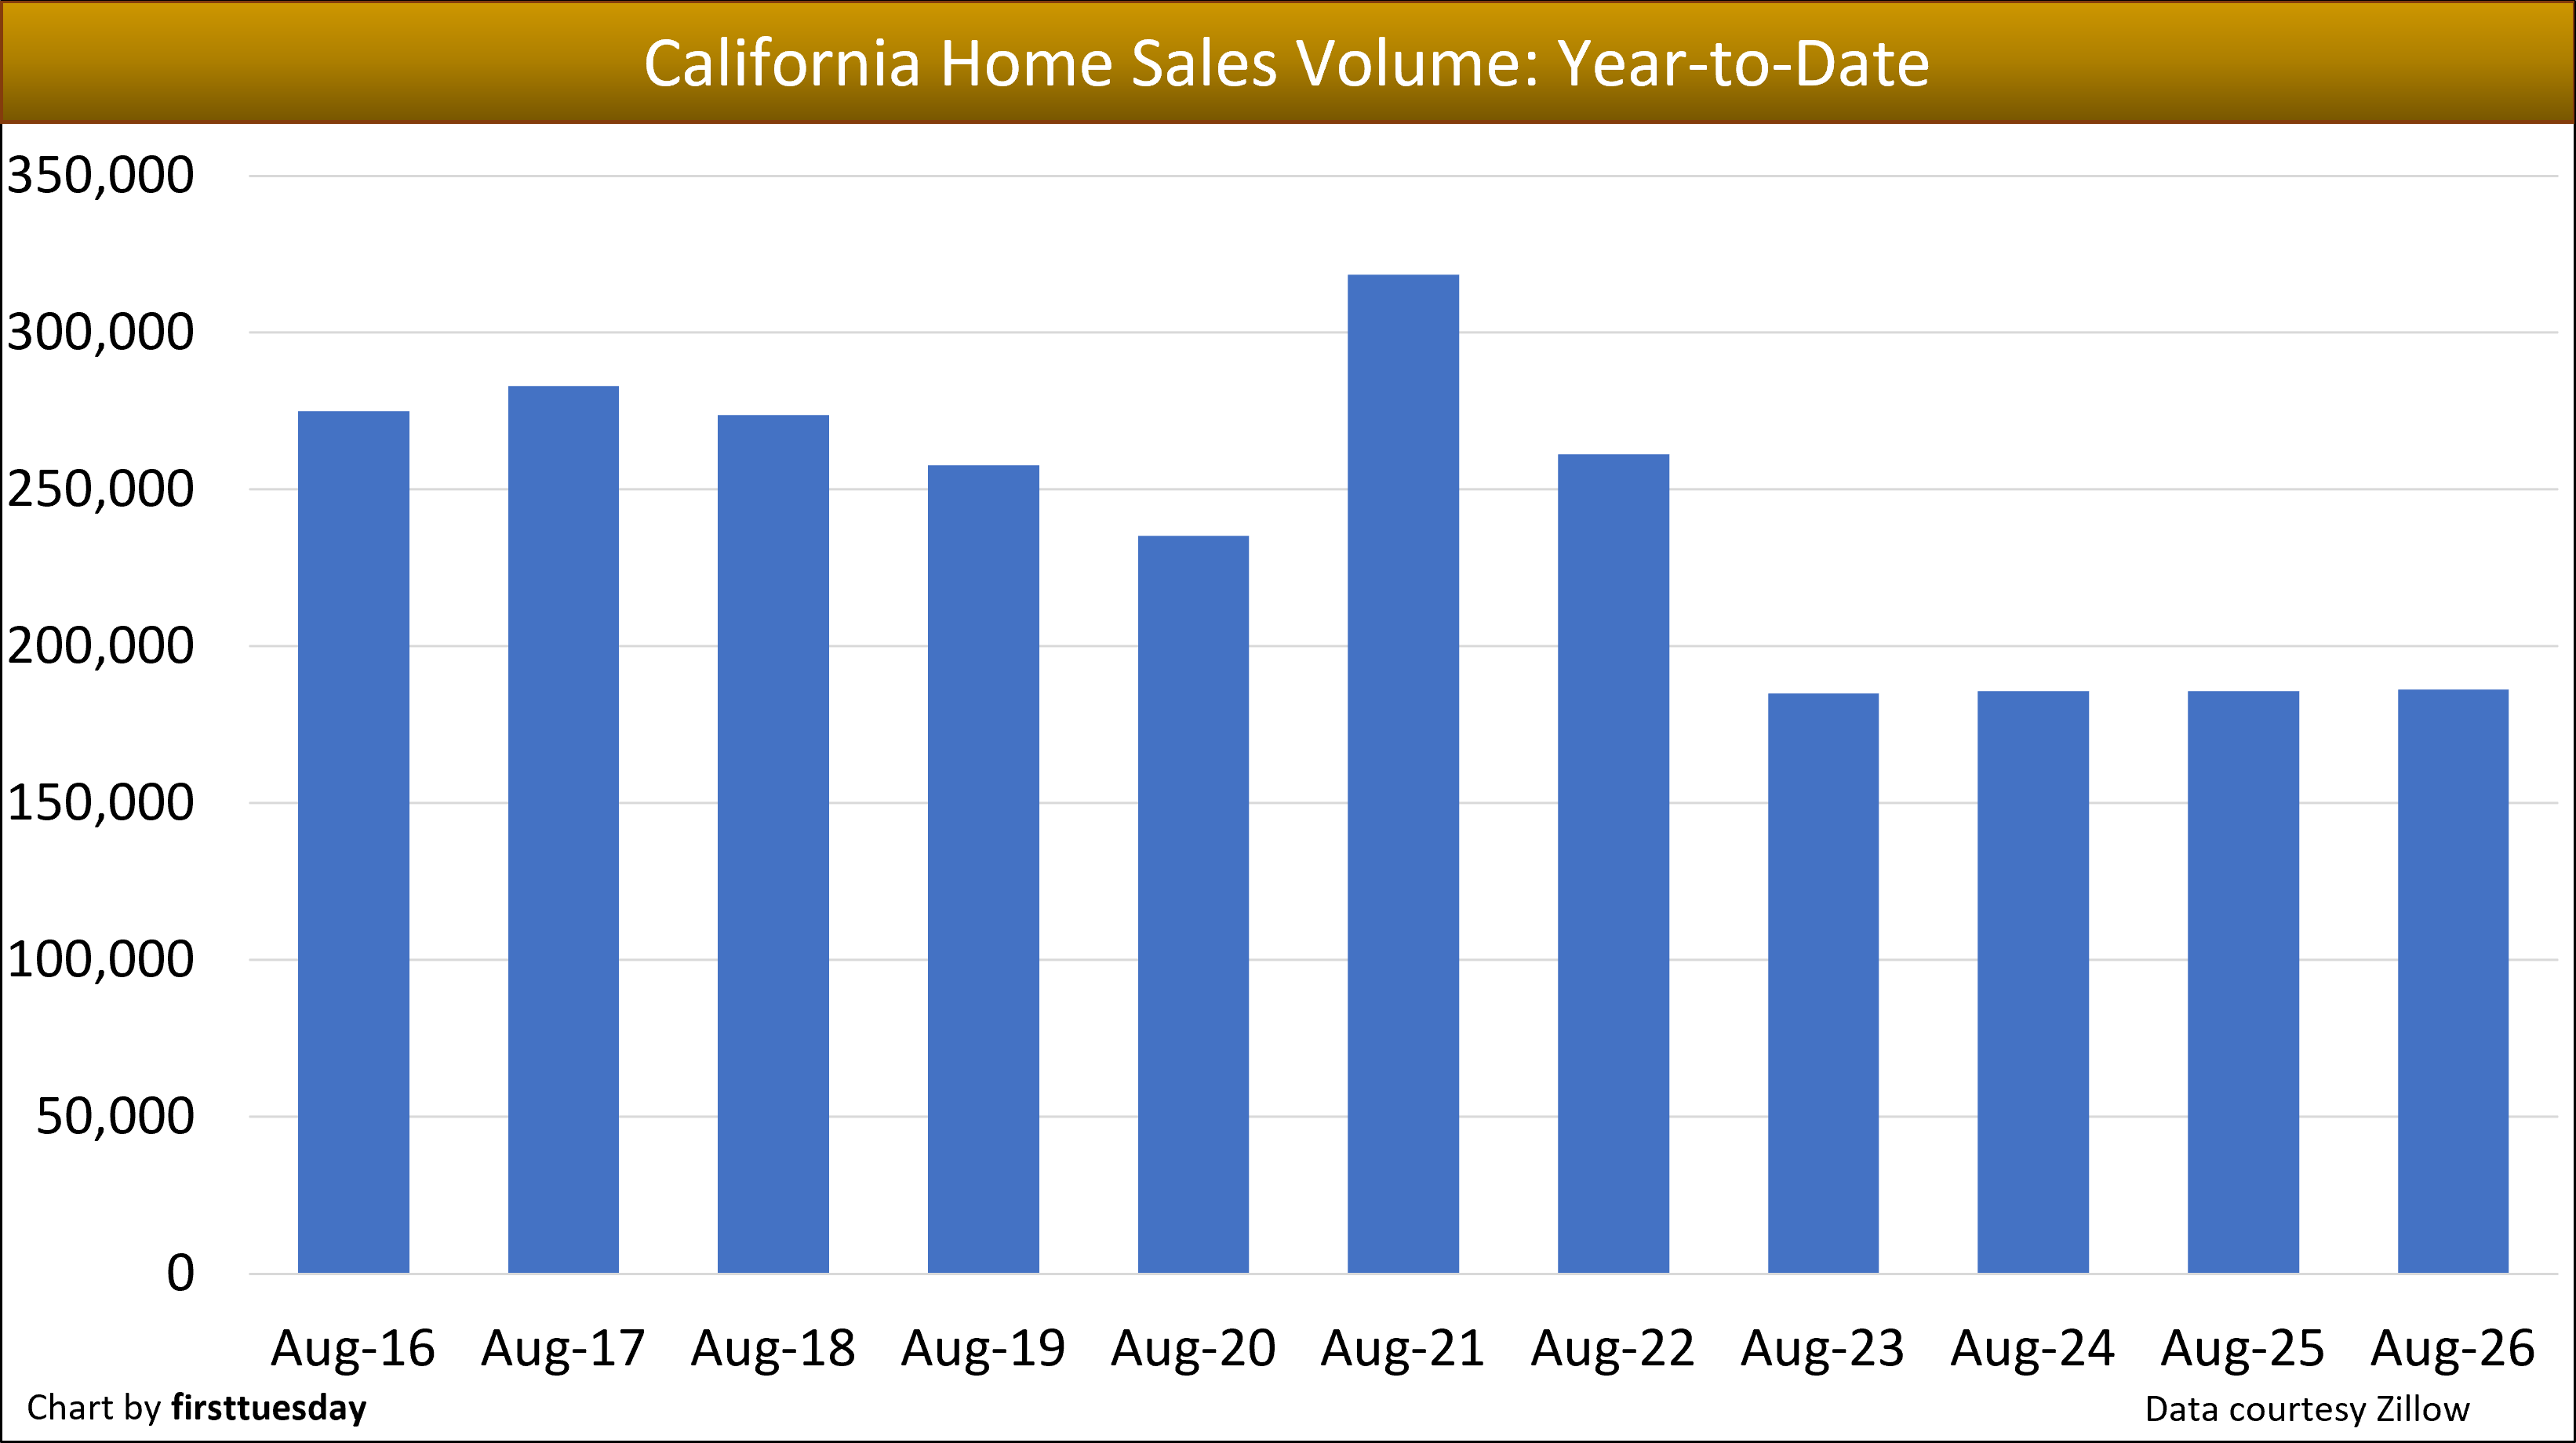 Chart update 9/24/26
| August 2026 | August 2025 | August 2024 | |
| Home sales volume year-to-date | 186,200 | 185,700 | 185,700 |
Year-to-date (YTD) home sales volume through August 2026 was substantially the same as the year prior. As of August 2026, YTD home sales volume is 0.2% above a year earlier. Compared to 2019, home sales volume YTD is 28% lower in 2026 as of August. 2019 was the last “normal” year for property transactions before the pandemic economy took over.
The present annual trend in sales volume is flat, but is expected to decline for the remainder of the year, due to:
- job uncertainty in the wake of the US-Iran War effort and trade wars disrupting the rate of job growth;
- high mortgage rates rising to reduce homebuyer ability and willingness to pay seller asking prices;
- a consistent quantity of all-cash buyers undeterred by interest rates or asking prices;
- reluctance of sellers to reduce asking prices to offset high mortgage rates and incentivize buyers;
- buyer agent failure to advise buyers to disregard asking prices and make offers at prices they qualify to pay;
- a steadily increasing inventory of property available for sale across the state causing buyers to wait before making a selection; and
- the real estate recession, yet to be declared, but four years underway throughout California.
Home sales in the coming years
The forward trend in California home sales is one of caution and delay for both buyers and sellers. Homebuyer income is growing but just above the rate of inflation, much improved from the less-than-inflation pace during the decade preceding the pandemic.
While wage increases caught up with consumer inflation, they were nowhere near enough to catch up with pandemic-peak home prices and post-pandemic mortgage rates. Home prices remain far above the mean price trendline, but the gap is narrowing as property prices run flat and wages increase.
The necessary price adjustment required to bring buyers to the table is resisted by sellers’ pricing stubbornness, known as the sticky pricing phenomenon. The likely result is continuing the post-2022 plateau of flat pricing that will meet up with the rise in the mean price trendline rather than prices dropping going into 2027 and its spring bounce.
firsttuesday forecasts annual home sales volume for 2026 will slip slightly from the level in 2025, as buyers continue to wait on the sidelines. The sales slump in 2026 will be the result of the tandem high or still rising levels of asking prices, mortgage rates and financial caution.
Sellers are also competing against the rising strain of buyers comparing the high monthly cost of ownership and the lower declining rent rates charged by landlords for similar housing — which reduces turnover and transactions.
The timeline for a real estate turnaround faces complications not experienced in recent decades. Government trade wars are raising the cost of both domestic and imported construction materials. Costs of owning real estate are compounded by the federal attack on the necessary migratory labor force for construction and maintenance of households. And now another American war in the Middle East with no end yet in sight.
The competitive broker
What’s a broker reliant on home sales to do until home sales volume provides abundance again?
SFR brokers and agents might consider adding transaction-related provider services to supplement their income in the present buyer’s market. Those who do add related services — provided only when the client signs a representation agreement — will restructure their practice as “all-service brokers.”
Transaction-related services originate primarily due to representing buyers, not sellers. When an office operation includes any of the services offered by providers to buyers, their agents maintain a standard of living, remain solvent and position the office for eventual growth. Notary, anyone? MLO? Property management? Home insurance?
Related video:




Wow nice post thank you for sharing !
Learn more about betrupees through clear guides and helpful platform details.
Find useful information about account access, features, and everyday usage.
Sales volume de viviendas en California se mantiene débil en 2026, con 18,500 cierres en febrero (-1.9% interanual) y una caída acumulada de 3.3%, reflejando cuatro años de mercado estancado debido a altas tasas hipotecarias, precios elevados, incertidumbre económica y menor interés de compradores, mientras el aumento de inventario y la cautela general continúan frenando la recuperación.
thxx
thx
thx
thank you
Sizde yöneticilik ile çok kolay!iralama veya kiralık bahis siteleri ile çok kolay!
Sizde yöneticilik ile çok kolay!iralama veya kiralık bahis siteleri ile çok kolay!