Why this article matters: The Buyer Purchasing Power Index (or BPPI) measures the change in the amount of mortgage money available to a typical homebuyer, varying due to mortgage interest rate swings.
Buyer Purchasing Power normalizes, not so for property pricing
The California Buyer Purchasing Power Index (BPPI) figure went negative, at -5.34 at the end of the third quarter (Q3) of 2026. This figure tells us a homebuyer with an annual income adjusted for the cost of living is able to borrow 5.34% less purchase-assist money today than a year ago.
The BPPI is calculated using the:
- average 30-year fixed rate mortgage (FRM) rate reported by the St. Louis Federal Reserve Bank;
- median income in California; and
- consumer price index (CPI) in Los Angeles.
A positive index number means homebuyers can borrow more money this year than one year earlier.
A negative index figure translates to a reduced amount of mortgage funds available to buy a home.
An index of zero means no year-over-year change occurred in the amount a buyer can borrow with their COLA-adjusted income. At a BPPI of zero or below, homebuyers cannot purchase the same home at a higher price — adjusted only for consumer inflation (2% to 3%) — than one year before unless they:
- resort to adjustable rate mortgages (ARMs)to extend their borrowing reach (which increases their risk of default);
- significantly increase their wages; or
- accumulate a larger down payment amount.
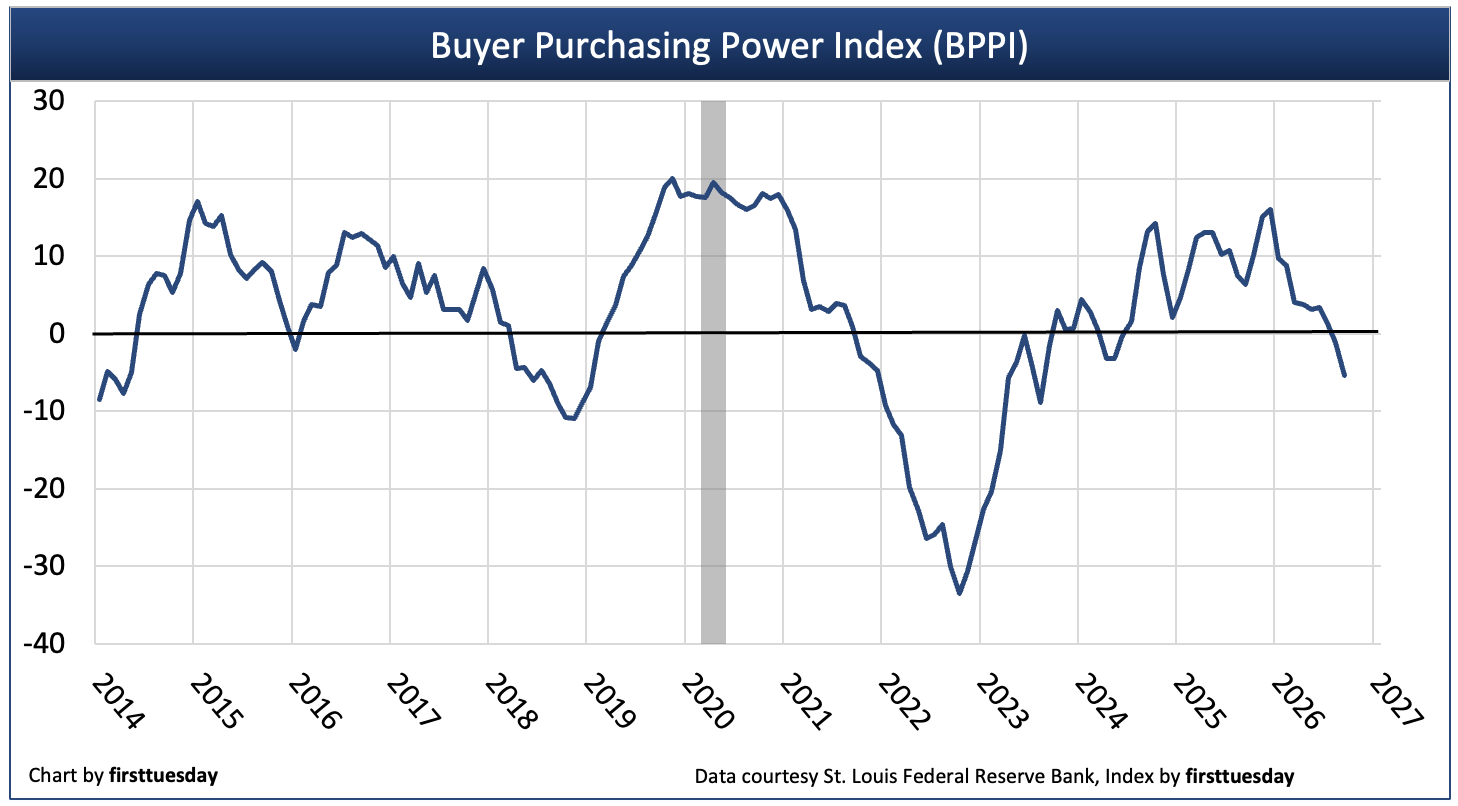
Chart update 10/28/26
| Q3 2026 | Q2 2026 | Q3 2025 | |
| Buyer Purchasing Power Index (BPPI) | -5.34 | +3.48 | +6.40 |
The effect of BPPI on home prices
In 2019, as the 2020 recession was shaping up, the BPPI moved positive after annually trending negative following the 2013 commencement of a half-cycle of rising mortgage rates. In 2020, the pandemic economy set in and the Federal Reserve took over the mortgage bond market and cut FRM rates in half. Thus, declining FRM rates in 2019-2021 kept the BPPI positive. To fully offset the advantages of the positive BPPI, home prices quickly increased around 30% year-over-year.
Heading into 2022, the BPPI took a dive deep into negative terrain to reflect lost borrowing capacity for homebuyers (and owners) as FRM rates more than doubled. In the same period, sales volume and prices peaked in unusually fast succession, an unfriendly omen for forward property sales volume.
Throughout 2023, the negative BPPI gradually rose to zero, reflecting a year-long “normalizing” of mortgage rates as the Fed got inflation under control.
Consider a household in Q2 2021 when the 30-year FRM rate averaged 2.8%. As a homebuying household, the household qualified to borrow a maximum of $480,000 to fund the purchase of a home. Now compare that mortgage amount with the amount available in September 2026 at the 30-year FRM rate of 6.9%. The same household income — with COLA adjustments — now qualifies the buyer to borrow just $376,000 — 22% less money to fund the purchase of the same home. Worse, home prices since Q2 2021 have increased, though have remain essentially flat since mid-2022.
Mathematically, an employed homebuyer’s borrowing capacity sets what they can pay for a home with their down payment and mortgage funding the price paid to acquire a home. Thus, today, the same price tag on the 2021 home is now 50% over the price the same borrower can pay today, before accounting for any added borrowing capacity for COLA wage increases over the four-year period (around 19%).
Critically, home prices received by sellers absorb the reduction in borrowed funds available to buyers. Economic reality offsets a rise in mortgage rates with a drop in property prices. The logic is that the present value (PV) of the increased interest paid on an FRM is offset by an equal drop in property prices since borrowing by a homebuyer is based on wages. In turn, wage increases are tied to consumer inflation, not assets valued at inflated seller asking prices.
An irony is involved. When FRM rates increase, seller pricing moves down very slowly, taking 24-to-36 months to fully absorb the diminution in funds available to buyers, called the sticky price phenomenon. Conversely, when FRM rates drop, seller pricing moves up rapidly, taking less than 12 months to fully absorb the additional funding available to the same buyer of the same home.
The difference in seller reaction time with rising FRM rates comes down to sellers’ natural resistance to lowering their asking price for a property that hasn’t, in their eyes, changed from yesterday’s prices. For a seller agent, it is comparatively easy to ask a seller to raise their asking price as for-sale inventory runs thin rather than insist they lower it to attract a buyer.
While home prices remain level in 2026 across California (except for the drop in high-tier property) as mortgage rates increase, 2027 home sales will weaken until either or both asking prices drop (or mortgage rates drop). However, today’s economic uncertainties and high inflation rates turn homebuyers more cautious, holding back many willing homebuyers from entering the market. Thus, in 2027, the low level of inventory for sale will rise as reduced homeowner turnover causing prices to falter.
The BPPI foreshadows home price movement
As the BPPI enters a recessionary period and eventually trends positive for mortgage-reliant buyers, the asking price for homes now in decline in the wealthy neighborhoods will ripple into mid- and low-tier housing. Price decline is a fundamentally different but positive condition for buyers compared to an also buyer-friendly positive BPPI figure. But when they evolve concurrently, as is likely by 2028, homebuyers become more willing to make offers.
Today’s high mortgage rate and flat pricing trends will likely continue well into 2027, ending in a rapid mid-year downward adjustment in asking prices by sellers who need to dispose of their real estate.
In the current 30-year half cycle of rising mortgage rates, which began in January 2013, the seller in the real estate market is adversely affected by a melting away of their home equity and thus the level of solvency. On the other hand, prospective buyers pay the same monthly amount for shelter at a maximum of 31% of their gross income when they maintain their standard of living during periods of rising mortgage rates.
A reallocation of national wealth is underway, long term. When FRM rates increase, investors in mortgage backed bonds (MBSs) – thus lenders – pick up an increased portfolio yield in interest earnings. The increased yield represents a shift in wealth equal to the present value (PV) of the increase in mortgage rates. This is reflected, eventually, in a reduction in the seller’s equity. Hence the reallocation.
The homebuyer’s financial position is always a constant – 31% of gross income equals the payment for shelter, whether it’s rent or mortgage payments (and ownership operating expenses). Homebuyers qualify for a maximum mortgage amount based on:
- their incomes and savings; and
- shifting interest rates.
Sellers are slowly discovering, as are seller agents, that the math of increased mortgage rates for a homebuyer’s purchase-assist funding leaves all property worth less in value.
Declining prices will likely bottom, forming a pricing trough around 2028 to 2030. As the pricing trough sets in, expect an initial arrival of speculators and investors to provide a short-term pick up in sales volume as a temporary “dead cat” price bump before we move out of the pricing trough. The recovery begins when prices start to rise without slipping for several months. Soon, ready and able buyer-occupants sense a rise in pricing and become willing buyers ready to buy, as they do in every recovery period.
During the decade ahead expect downward pressure on prices for all types of property due to the foreseeable long-term rise in the cost of mortgage funds.
BPPI in the years ahead
Accordingly, the long-term outlook for the BPPI through the 2030s will annually remain just below zero, as mortgage rates resume their cyclical rise.
An agent’s plans for sales in real estate during the next several years need patience and a very different approach from 1983 until 2013 decades driven by constant decline in mortgage rates.
To keep the inventory of homes-for-sale changing hands at an optimal pace, sellers on the advice of their agents need to lower prices to accommodate buyer purchasing power or pull their properties off the market.
Proactive seller agents may need to fire sellers who harbor deal-killing illusions of past pricing.
Related article: