Introducing our latest video series: Turning Tenants into Buyers.
This series breaks down the core mortgage fundamentals every DRE licensee needs to master when guiding first-time buyers toward homeownership. Throughout the series, we illustrate the distinct financial advantages of purchasing a home with a 20% down payment.
In this third episode, we’ll illustrate how making a 20% down payment rewards first-time homebuyers with savings received through reduced mortgage payments over the life of the mortgage and the avoidance of mortgage insurance.
Watch the second episode here.
Calculating opportunity costs for first-time buyers
The use of savings for a down payment presents a dilemma about alternatives, called opportunity costs. The opportunity costs of investing savings in a home are the missed potential alternatives when using the savings in a venture rather than earning interest.
To save for a down payment, a first timer must establish a monthly regimen and have the patience to maintain it. A personal savings effort avoids any risk-of-loss in the future which is a first timer’s long-term financial goal. When using cash to reduce mortgage principal, the savings are received through reduced mortgage payments over the life of the mortgage.
Putting cash into a down payment “costs” a buyer around 3% interest annually from a savings account or investment elsewhere. The amount saved when reducing the amount of principal borrowed, is the amount of mortgage interest avoided at, say, 6.5%.
Thus, an additional 3.5% is earned on the down payment by using the savings to buy the home — getting 6.5%, not 3% on the savings.
Homebuyers who invest more capital — cash — into ownership up front are rewarded in the short and long term with significant cost reductions and a far greater return on investment over the life of the mortgage.
The responsibility is on the buyer and their agent to understand the limits of a potential homeowner’s ability to meet the financial obligations of ownership.
Monthly mortgage insurance eliminated by 20% down
First-time buyers are often tantalized by the appeal of purchasing a home with little to nothing as a cash down payment. The instant satisfaction of a pivot into expensive housing conditions compared to the amount of rent the same or a comparable residence would command from a tenant can be socially irresistible.
Critically, the ability to make a 20% down payment indicates the buyer is solvent, qualified and more likely to close. Similarly, the seller broker knows a significant down payment is advantageous to the seller as it indicates lower risk of a fallout and a smoother transaction.
For mortgage funding with less than a 20% down payment, the mortgage loan originator (MLO) offsets their elevated risk of loss by requiring mortgage default insurance. The annual premium is nearly 1% of the mortgage balance. This premium is paid by the homebuyer with the mortgage payments, treated no differently than additional interest.
Suddenly, a mortgage rate of 6.5% FRM actually totals 7.2% — the penalty for not savings a 20% down payment.
When the buyer does NOT make a 20% down payment, this mortgage insurance comes in two forms:
- mortgage insurance premiums (MIPs) when insured by the Federal Housing Administration (FHA); or
- private mortgage insurance (PMI) when insured by private insurers.
When the buyer makes a full 20% down payment, the avoided mortgage insurance cost totals far more than the loss of interest on the savings used to meet the 20% threshold.
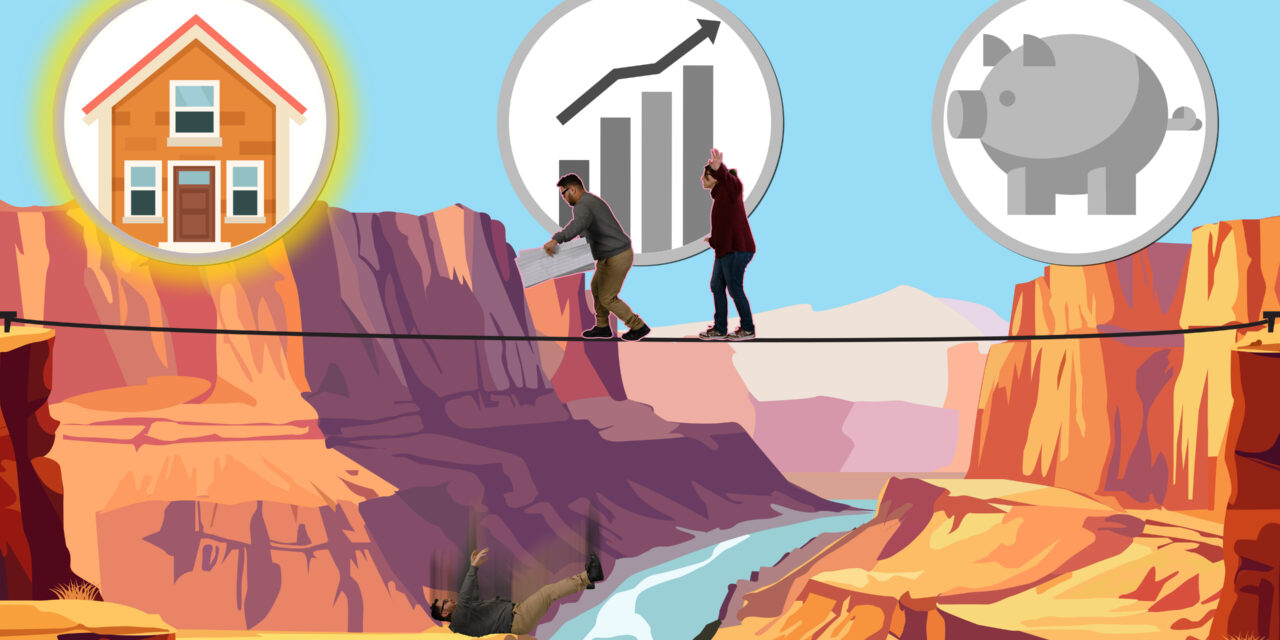
A choice to save hangs in the mortgage balance
These different rates alone undersell the story about all the costs. Unlike the FHA’s MIP, the PMI version of default insurance ends once a mortgage balance reaches an LTV of 80%. Of course, with a 20% down payment this default insurance premium is avoided, saved to be put to better household use — that standard of living thing.
Contrary to historical wisdom, a higher down payment only nets a lower interest rate when a buyer goes with an FHA-insured mortgage. A conventional mortgage does not benefit from a better rate when a buyer has saved up a 20% down payment. However, they do avoid the larger insurance premium MLOs require for smaller down payments, paid on the entire principal balance on the mortgage.
Even when sharing the commitment to save with another person, clients of a well-informed buyer agent are guided to other cost reductions and long-term savings.
Editor’s note — Stay tuned! The remainder of this series continues to illustrate how an agent or broker fully and effectively communicates the costs of a worthwhile mortgage-leveraged homeownership to their prospective buyers and the long-term financial security a 20% down payment provides.